Executive Summary: A UCC search is indexed around the debtor name, so searching a DBA, shortened name, or wrong entity can create a clean-looking result for the wrong subject. For VP Risk; Underwriting Director, the real question is why legal-name resolution must precede UCC filing retrieval in an alternative-lending workflow. The workflow must preserve exactly what was searched, what the source returned, which scope remained uncovered, and what the lender decided.
Why Does This Ucc Filing Decision Need Its Own Control?
What fails when the source result is treated as the decision?
A technically valid response can still answer the wrong entity, jurisdiction, time, or assertion. The product returns source data within a documented scope. The customer owns identity resolution, legal sufficiency, exceptions, credit policy, and any downstream action.
What governing idea should the team use?
Resolve the registered legal entity before the UCC request, preserve historical and alternate names, and treat every search result as a response to the exact debtor name and jurisdiction used. That principle gives risk, operations, and engineering the same boundary and prevents an unavailable or uncovered source from becoming a clean result.
The result is only as specific as the subject, source, jurisdiction, query, time, and coverage recorded with it.
What Does the Current Product Actually Support?
Which behavior is verified?
Cobalt's UCC data is delivered through SOS Search, which can first return the registered title and possible alternatives, then include UCC filing data for the selected state when `uccData=true` is used. Confirm the current request contract in Cobalt's public API documentation before implementation.[1] Cobalt's related implementation guide shows the product in a lender workflow.[2]
Which limitations must remain visible?
A no-record result is only as reliable as the debtor name, jurisdiction, search logic, source timing, and product coverage. Cobalt is a data source, not legal counsel or a lien-priority decision engine. Do not convert those boundaries into small print after a broad promise. Put coverage, delivery, source completeness, and customer decision ownership beside the workflow step they constrain.
What Do Filing Offices Say About Debtor Names?
Why is the exact name material?
California says filers are responsible for the exact legal name of a registered organization and identifies registration documents as the best source.[7] Its search rules warn that a debtor-name search does not return name variations unless separate searches are requested.[8]
New York's rules likewise describe a name-indexed search and exact-name processing.[9] These state examples do not establish one national search opinion, but they show why application normalization and entity resolution cannot be skipped.
Which Name Set Should the Lender Preserve?
What belongs in the search plan?
Keep the application name, DBA, resolved legal name, state entity ID, prior legal names, formation state, relevant foreign registrations, and the reason each name or jurisdiction is searched. The lender's counsel and policy determine sufficiency.
What result should never be called clean?
Do not call a result clean when the entity remains ambiguous, only a DBA was searched, the required jurisdiction is unsupported, the source was unavailable, or historical names required by policy were omitted. Use precise dispositions such as no filings returned for searched name and jurisdiction at stated time.
What Workflow Should Risk and Engineering Implement?
Which sequence is reproducible?
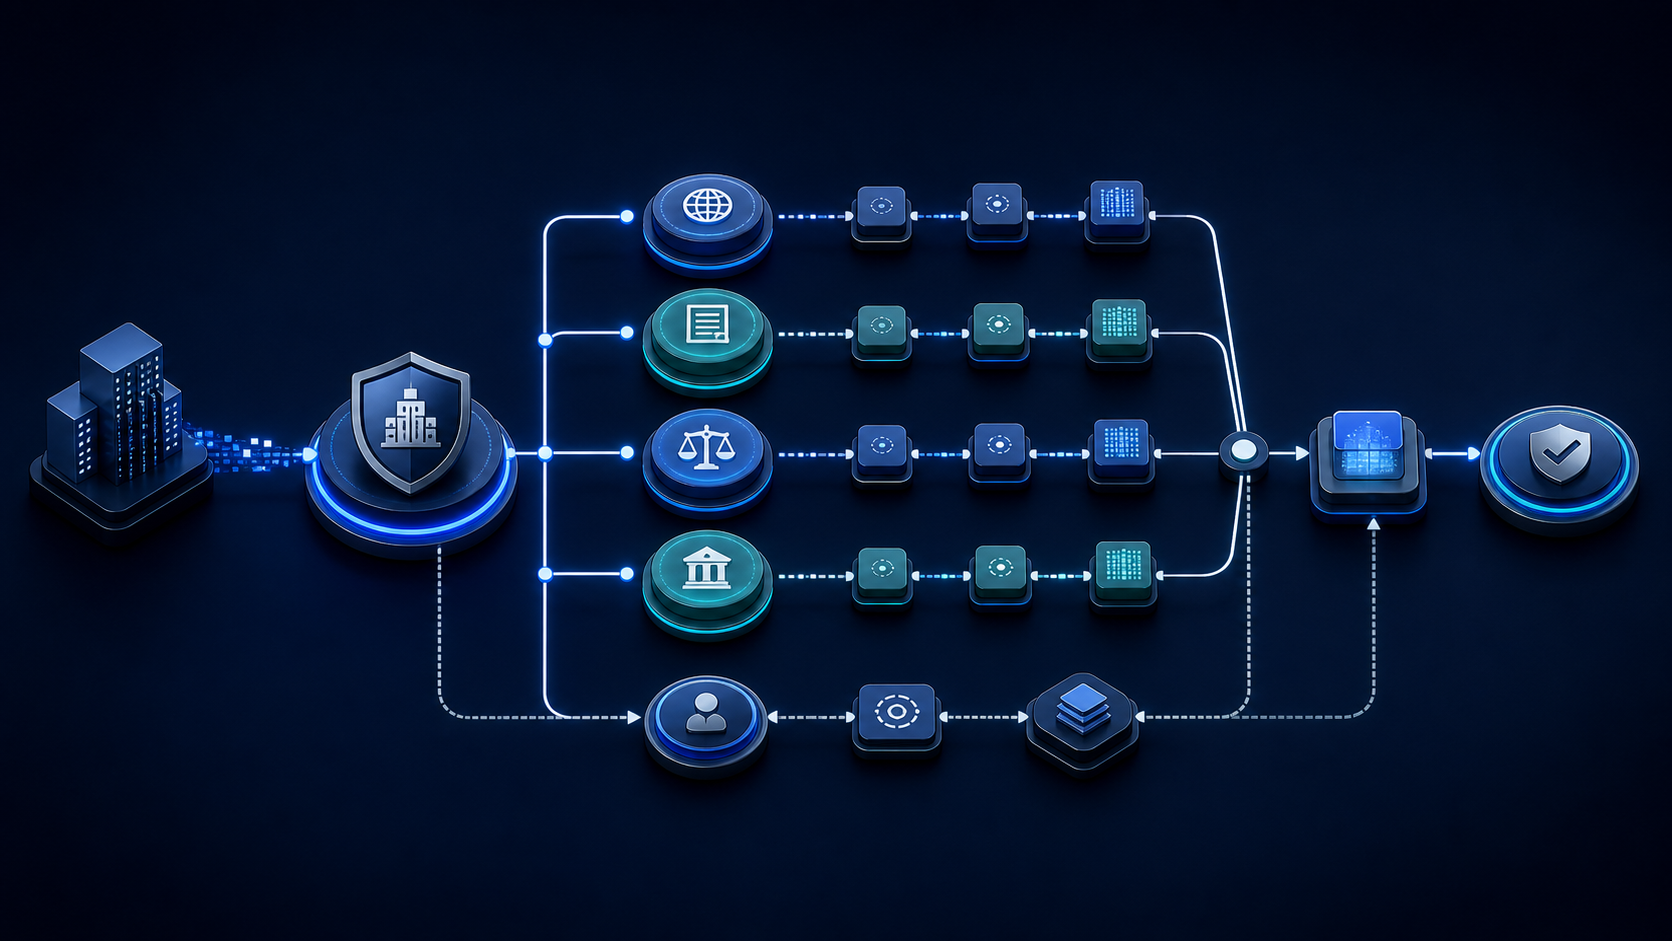
• Preserve the submitted borrower and DBA. Preserve the evidence, owner, and closure rule for this step.
• Resolve the legal entity in the correct state. Preserve the evidence, owner, and closure rule for this step.
• Capture the exact registered title and entity ID. Preserve the evidence, owner, and closure rule for this step.
• Identify historical names required by policy. Preserve the evidence, owner, and closure rule for this step.
• Confirm supported UCC jurisdiction coverage. Preserve the evidence, owner, and closure rule for this step.
• Run searches under approved debtor names. Preserve the evidence, owner, and closure rule for this step.
• Review filings and source limitations. Preserve the evidence, owner, and closure rule for this step.
• Store the search set and lender disposition. Preserve the evidence, owner, and closure rule for this step.
Each step should produce a record with source, timestamp, customer owner, and disposition. The lender should be able to reproduce why the source was queried, why the result belonged to the file, and what scope was still open.
Where should automation stop?
Stop when the subject is ambiguous, required jurisdiction is unknown or unsupported, the source is unavailable, the response cannot be joined to the request, a required field is missing, or the result requires legal interpretation. The stop should create an owned exception, not a generic error or silent pass.
How Should Evidence and Customer Interpretation Be Stored?
Which records should remain separate?
Keep the original request, raw authorized response, normalized display, coverage result, customer rule version, reviewer disposition, and later correction as linked records. This prevents a later mapping change from rewriting what the source actually returned.
What belongs in the operating screen?
Show the exact subject searched, jurisdiction, source and check time, coverage state, material returned fields, source limitations, pending dependencies, owner, due time, and allowed next action. Keep sensitive inputs and unrestricted raw payload access behind the customer's access controls.
Which Source Boundaries Matter Most?
Why should official systems remain visible?
The authoritative source depends on the product. A UCC filing workflow must preserve the product documentation, original source, jurisdiction or service context, exact request, and retrieval time. It must not borrow a broader conclusion from a different verification source.
How should changing source behavior be handled?
Record retrieval time, product mode, and current documentation. When coverage, schema, source availability, or state rules change, update future requests and mappings without rewriting historical evidence. Route any material conflict to the higher-authority source named by the current product expert.
Which Filing-Office Rules Ground the Search Design?
What do state examples show?
Cobalt's search guide distinguishes debtor, secured-party, and collateral review.[3] Its coverage guide explains why state availability must be checked before a workflow promises a result.[4] The Uniform Law Commission identifies Article 9 as the secured-transactions article.[5]
California describes its Secretary of State as the central filing office for specified financing statements and lien documents.[6] It places responsibility for the registered organization's exact legal name on the filer.[7] California search rules say the submitted debtor name controls the query and warn that variants may require separate searches.[8] New York also documents name-indexed search logic.[9] Florida states that its registry uses state-required search logic and cautions that search behavior differs across states.[10]
These sources support a coverage-first, exact-input workflow. They do not replace counsel on legally sufficient searches or filing priority.
What Should the Team Test Before Production?
Which cases belong in the test set?
Use a clean result, no-result response, ambiguous subject, unsupported scope, unavailable source, duplicate delivery or retry, malformed or incomplete data, and a case that requires human interpretation. Confirm each produces the expected owner and does not create an automatic credit conclusion.
What indicates a broken integration?
The integration is broken when it loses the original query, cannot distinguish unsupported from no records, overwrites source values, fails to join a response, creates duplicate dispositions, exposes sensitive data broadly, or lets a timeout become a negative result.
How Should the Control Be Measured?
Which operating measures are useful?
Track completion by coverage state, ambiguous-subject rate, source-unavailable rate, pending age, duplicate suppression, manual-review reasons, overrides by policy version, and results without a complete audit join. Segment by product, jurisdiction, and intake channel.
Which claims should those measures not support?
These counts can show process quality. They do not prove lower defaults, fraud prevention, legal compliance, improved approvals, or customer ROI without separate evidence. Keep the source result and business outcome analysis distinct.
Where Does Cobalt Fit Among the Alternatives?
What should a buyer compare?
Compare manual official-source searches, an internal connector, an existing vendor, and Cobalt on coverage, source traceability, input and output contract, delivery behavior, exception handling, and maintenance. Do not compare on an unsupported national, real-time, or decisioning promise.
Cobalt supplies the documented UCC filing data route. The lender supplies subject resolution, policy, legal interpretation, credit authority, and any unsupported fallback. That is the practical answer to why legal-name resolution must precede UCC filing retrieval in an alternative-lending workflow.
What is the next useful test?
Use one ordinary file and at least four exceptions from this article. Confirm the exact request, response, coverage, timestamp, customer rule, reviewer, and closure reason survive end to end.
To test current behavior against your own workflow, schedule a Cobalt Intelligence demo. Bring representative subjects, jurisdictions, dependencies, and exception rules.