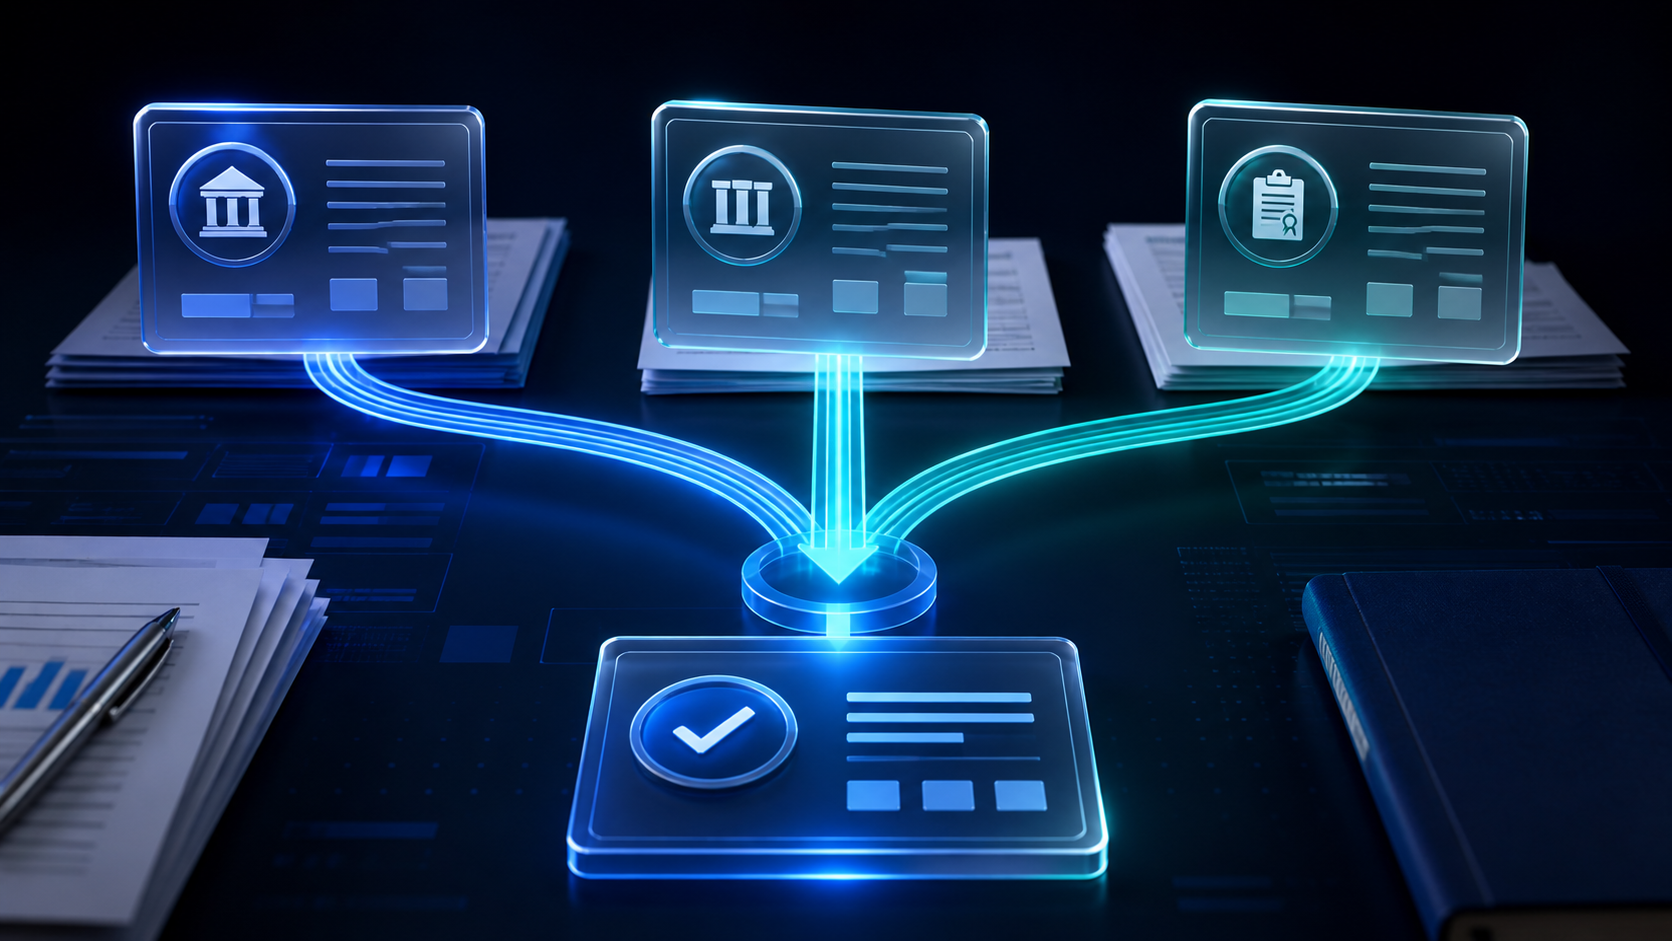
Executive Summary: Alternative lenders financing contractors often receive three apparently positive records: a Secretary of State entity result, a federal name and EIN match, and a state or local contractor license. Those records do not become one verified business merely because each screen is green. Before funding, the lender must join the legal entity, tax identity, credential holder, applicant, and receiving account into one explainable relationship. The three sources answer different questions. An SOS office reports what a jurisdiction publishes about a registered entity. An EIN check tests a submitted legal-name and tax-ID pair. A licensing authority reports a credential issued for a regulated trade or jurisdiction. None of them proves account control, beneficial ownership, job legitimacy, or repayment capacity.
Why Are Three Green Checks Not One Verified Contractor?
A lender can receive a valid result from every source and still be looking at different parties. A trade name may appear on the application, a corporation may hold the license, a related LLC may receive the financing, and a third entity may own the bank account.
What assertion does each source support?
• SOS record. The named entity appears in a state registry, with whatever status and fields that state makes available.
• Name and EIN result. The submitted legal-name and EIN pair matches the source record.
• License record. A licensing authority associates a credential number with a named person or business under its own rules.
• Application. The applicant claims that these records belong to the proposed borrower.
• Bank evidence. The account record supports who controls the destination for funds.
• Credit file. The lender's policy determines whether the assembled evidence supports a financing decision.
The IRS explains that TIN matching compares a supplied name and TIN combination. It is not a public search for an unknown EIN.[1] California's contractor lookup similarly tells users to search a specific licensing record and review the record shown by the licensing board.[2]
A verification workflow is complete only when it can explain why the entity, tax pair, license, applicant, and receiving account belong in the same file.
Which Identity Should the Lender Establish First?
Begin with the proposed financing recipient. Capture its legal name, DBA, EIN, formation or registration state, state entity number, license number, and intended bank account as separate fields.
Why should a DBA remain separate?
IRS corporate guidance explains that the name control is derived from the legal name associated with the EIN and that DBA text is not part of that control.[3] A truck, storefront, invoice, or website may display a trade name while the tax and state records use a legal entity name.
Do not overwrite the applicant's original value. Preserve both the submitted name and the normalized legal name used for verification. That makes later review reproducible and prevents an analyst from silently changing the subject of the check.
What should intake collect?
1. Submitted legal name and DBA.
2. EIN, stored under the lender's sensitive-data controls.
3. Formation state and every relevant foreign-registration state.
4. State entity identifier.
5. Contractor license number, type, and issuing authority.
6. Applicant and guarantor roles.
7. Bank-account holder and financing recipient.
The license number matters because Cobalt's documented contractor workflow requires it as an input. The current confirmed product coverage is California, Florida, New York through New York City Department of Buildings, and Texas. It is not a nationwide contractor-license search.
How Should SOS Data Anchor the Entity?
Use the relevant state registry to establish the legal-entity candidate and its state identifier. State records vary in status language, officer fields, addresses, identifiers, and availability. California publishes definitions for its business-search fields and warns that the status of a foreign entity in California concerns its registration in California.[4]
What should the workflow preserve?
• Exact query and jurisdiction.
• Candidate records returned.
• Selected state entity ID.
• Legal name and normalized form.
• Status exactly as the state returned it.
• Source timestamp and availability.
• Reviewer or rule that selected the candidate.
Do not translate every unfamiliar status into active or inactive. Preserve the state value, then apply the lender's documented policy. If several candidates remain plausible, stop the automatic route and request stronger identity evidence.
For a deeper treatment of the two federal and state assertions, see EIN Verification and SOS Data: The Two-Source Pattern.
Where Does EIN Verification Fit?
Run the name and EIN check after identifying the intended legal entity and before a credit approval or disbursement can rely on that identity. Cobalt's public documentation describes required business-name and TIN inputs and returns the source result with service status and timing context.[5]
submitted application
  -> SOS candidate selected
  -> legal name chosen for EIN check
  -> match, mismatch, or unavailable route
  -> license holder reconciled
  -> account holder reconciled
  -> lender decision
What does a match not prove?
A match does not discover owners, confirm that the applicant controls the entity, prove that the license covers the proposed work, or establish repayment capacity. It also does not verify that the destination bank account belongs to the contractor.
Treat the response as one timestamped identity assertion. The lender owns the rule that determines what happens next. Why EIN Verification Belongs in Pre-Funding, Not Post-Approval explains why correction is safer while the file is still reversible.
How Should the License Record Be Reconciled?
Licensing authorities operate for their own jurisdictions and trades. The credential may belong to an individual qualifier, a corporation, or another named business. The lender should not assume the holder structure without reading the record and the issuing authority's definitions.
Which fields need comparison?
• License number and type.
• Issuing authority and jurisdiction.
• Holder name exactly as returned.
• Related business name where published.
• Status and expiration or issue dates where available.
• Disciplinary information where the authority exposes it.
• Relationship between the holder and financing recipient.
California CSLB advises users to verify the license and review the personnel listed on the license record.[6] Florida provides a public license-search route through its Department of Business and Professional Regulation.[7] These systems are not interchangeable, and a result in one jurisdiction does not prove authority in another.
If the license belongs to a related entity or individual qualifier, collect the evidence that connects that holder to the borrower and proposed work. A relationship can be legitimate without being implicit.
What Should the Exception Table Do?
Create dispositions before production deployment. Every non-clean case needs one owner, next action, and closure rule.
• All three identities agree. Continue to account and credit review.
• DBA differs from legal name. Preserve the alias and verify the legal entity.
• EIN mismatch. Request corrected legal-name or tax evidence and rerun the exact pair.
• EIN source unavailable. Retry within policy or hold. Do not convert unavailability into a pass.
• License holder differs. Request relationship and job-scope evidence.
• License is outside confirmed coverage. Use the issuing authority's documented lookup or an approved manual fallback.
• Several SOS candidates exist. Stop automatic selection and resolve the entity identifier.
• Bank holder differs. Require account-control or intercompany evidence before disbursement.
IRS Publication 1281 provides correction procedures for missing or incorrect name and TIN combinations in its reporting context.[8] The operational lesson is useful here: a mismatch is a correction or investigation signal, not a fraud label.
What Evidence Should the Credit File Retain?
Store enough context to reproduce the decision without retaining unnecessary sensitive data in broad analyst views.
Minimum audit record
1. Original application values.
2. Selected SOS record and state entity ID.
3. Exact name and masked EIN submitted for matching.
4. Match status, reason, service status, and timestamp.
5. License query, record, authority, and timestamp.
6. Bank-holder comparison.
7. Exception evidence and reviewer disposition.
8. Policy version used by the lender.
The IRS instructions for Form W-9 explain the requester's role in obtaining the payee's certified name and TIN.[9] A W-9 can support an exception path, but it should not erase the prior input or source response.
What Should Teams Monitor After Launch?
Measure whether the workflow resolves identity, not merely whether the APIs respond.
• Mismatch rate by intake channel.
• DBA-related correction rate.
• Multiple-candidate SOS rate.
• License-holder relationship exceptions.
• Unsupported-jurisdiction fallbacks.
• Source-unavailable retries and aging.
• Bank-holder disagreements after all three source checks passed.
• Overrides by policy version and reason.
These measures reveal intake defects and coverage gaps. They do not, by themselves, demonstrate credit performance.
What Is the Practical Pre-Funding Sequence?
Establish the proposed borrower, locate the state entity, validate the legal-name and EIN pair, reconcile the license holder, then compare the destination account. Only after those identity joins are explainable should the file proceed to credit analysis and funding controls.
Cobalt can supply documented TIN/EIN, SOS, and supported contractor-license results. The lender supplies application context, relationship evidence, policy, and the final decision.
Ready to test the three-source identity join on a clean file and two exception cases? Schedule a Cobalt Intelligence demo and bring the state, tax, and licensing fields your current workflow retains.