Executive Summary: An EIN match is useful in business-purpose real estate lending only after the lender knows which legal entity is borrowing, which entity owns the property, which entity generates the cash flow, and which people are acting for each one. A clean tax-identity result for the wrong special-purpose entity does not repair a confused borrower structure. The safe workflow starts with an entity-role map. It then validates the required legal-name and EIN pairs, reconciles state records and property evidence, and keeps ownership, account control, and credit analysis in their proper lanes.
Why Does Real Estate Lending Create an Entity-Role Problem?
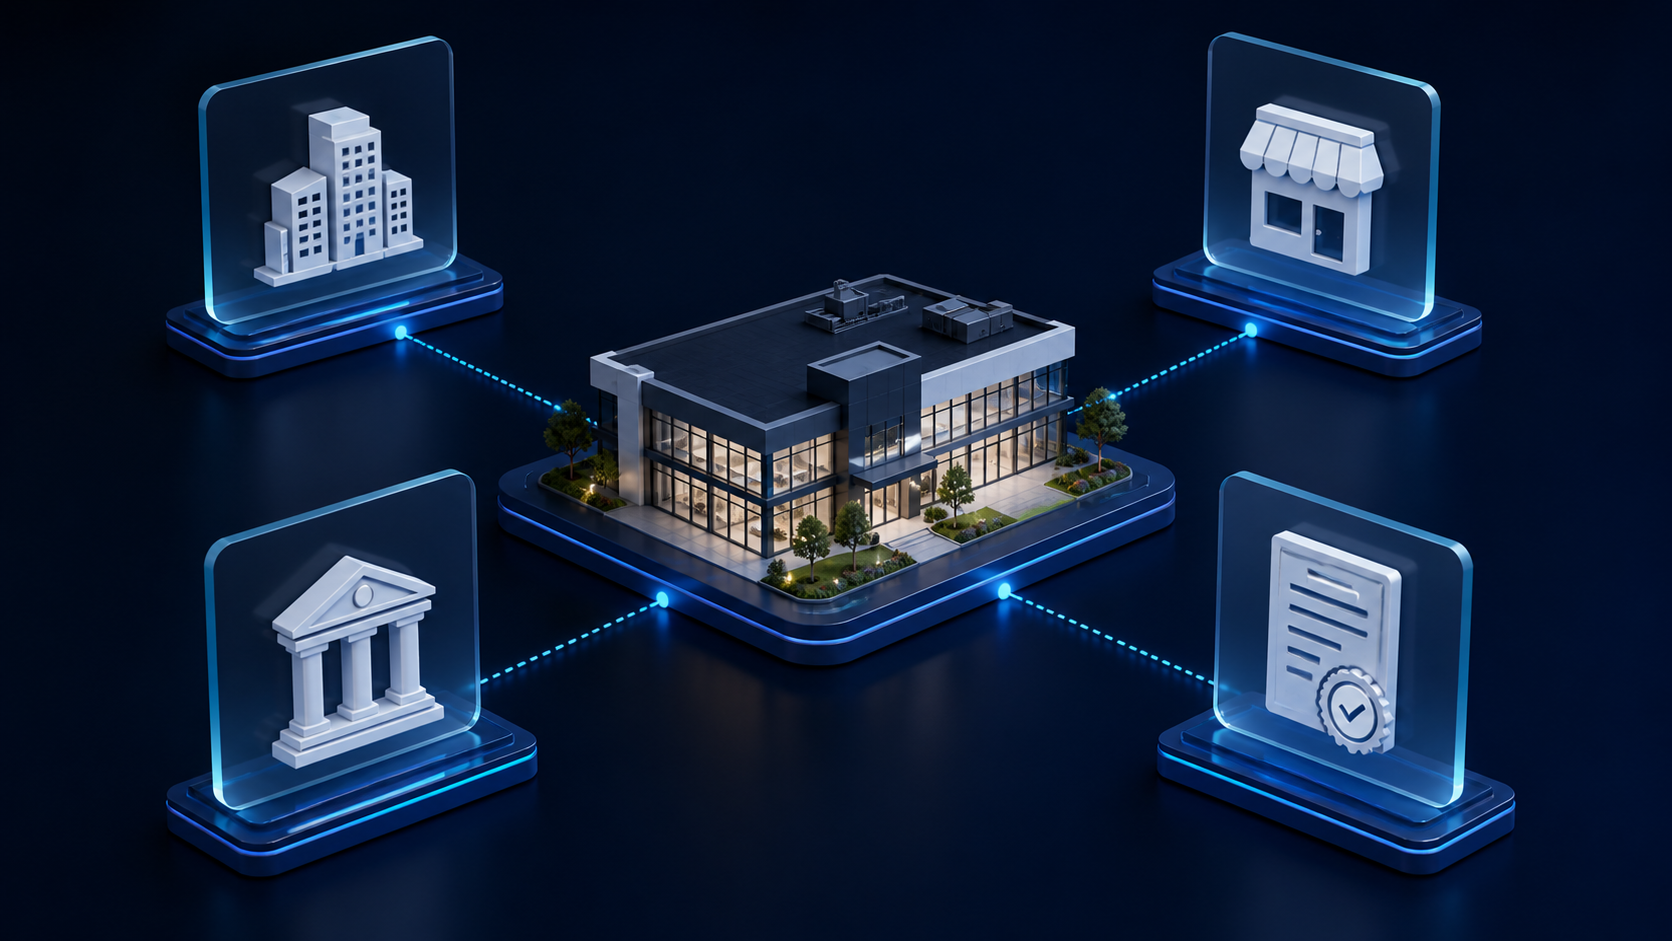
Business-purpose property transactions often involve more than one legal party. A special-purpose LLC may hold title, an operating company may generate revenue, a management company may collect rent, and one or more individuals may guarantee the obligation.
Which roles must be named?
• Borrower. The legal party signing the credit agreement.
• Title holder. The party shown in the authoritative property record or title evidence.
• Operating company. The business generating the cash flow used in underwriting.
• Property manager. The party collecting rent or managing operations.
• Bank-account holder. The party controlling the account used for proceeds or payments.
• Guarantor. A natural person or entity providing a separate obligation.
• Beneficial owner. A natural person identified under the applicable institution's rules and procedures.
These roles can overlap, but the lender should prove the overlap rather than assume it. State formation, federal tax identity, property title, and account control arise from separate record systems.
Verify each legal party for the role it actually performs in the transaction.
What Does EIN Verification Establish?
The IRS TIN Matching program compares a supplied name and TIN combination for eligible payer workflows.[1] Cobalt's documented TIN/EIN endpoint likewise validates a submitted business name and EIN. It does not discover an unknown EIN, verify title, identify beneficial owners, confirm a bank account, value a property, or make a credit decision.[2]
Why is the legal name important?
IRS corporate guidance explains that the name control is derived from the legal name associated with the EIN and generally excludes DBA text.[3] The property brand, building name, or management-company trade name may not be the tax name of the borrower.
Preserve the original application value, the legal name selected for matching, the masked EIN, the result, and the timestamp. If either input changes, the old result does not prove the new pair.
How Should the Lender Build the Entity-Role Map?
Create the map before running automated decision rules. One row should represent one legal party, with roles attached to that row.
legal party -> state entity -> EIN pair -> transaction role -> supporting evidenceWhat fields belong in the map?
1. Exact legal name and DBA.
2. Formation state and state entity identifier.
3. Foreign-registration states relevant to the transaction.
4. Masked EIN and verification result.
5. Borrower, owner, operator, manager, guarantor, and account roles.
6. Property or account evidence supporting each role.
7. Relationship evidence between different parties.
8. Exception owner and disposition.
SBA guidance distinguishes formation from foreign qualification and notes that a business active in more than one state may need registrations outside its formation state.[4] A state hit in the property state therefore may represent a foreign registration rather than a separate company.
Where Should SOS and Property Evidence Enter?
Use Secretary of State data to establish the entity candidate, jurisdiction, identifier, and state-specific status fields. Use property evidence to establish the title or collateral party. Do not ask one source to prove the other's assertion.
California's business-search definitions show why the distinction matters: the state publishes its own status terms and explains that a foreign entity's California status concerns its registration in California.[5]
What should happen when names differ?
• Preserve both exact values.
• Check for a documented legal-name change or foreign-registration record.
• Keep a DBA as an alias, not a replacement tax name.
• Resolve suffix and formatting differences without changing the subject.
• Require relationship evidence when the parties are genuinely different.
• Stop the automated path if several plausible entities remain.
For the federal and state identity layers, see EIN Verification and SOS Data: The Two-Source Pattern.
Which EINs Should Be Verified?
Verify the tax pair for every legal party whose identity is material to the lender's policy. That will often include the borrower. It may also include a separate operating company or guarantor entity when the lender relies on its cash flow or obligation.
When is one EIN not enough?
One match is not enough when the credit file relies on another entity's revenue, property, guarantee, or account. For example, a property-owning LLC may borrow while an operating company provides the repayment cash flow. The workflow should validate both legal identities and document the relationship that permits the lender to rely on the operating company's evidence.
Do not run an EIN check against a natural-person guarantor as if the person were a business entity. Classify the subject first and use the evidence appropriate to that role.
How Should Results Route the File?
Create a decision table before launch.
• Match with consistent entity role. Continue to the next identity and credit controls.
• Match for a different related entity. Hold until the relationship and transaction role are documented.
• Name mismatch. Compare the application, state record, and tax documentation; correct and rerun when appropriate.
• Source unavailable. Retry or hold under policy. Do not interpret unavailable as verified.
• Property owner differs from borrower. Require title, organizational, and legal-review evidence appropriate to the transaction.
• Account holder differs. Require account-control or authorized-payment evidence.
• Unresolved candidate. Send to a named reviewer rather than selecting by name similarity alone.
IRS Publication 1281 illustrates a correction process for missing and incorrect name/TIN combinations in its reporting context.[6] A mismatch is not, by itself, evidence of intent or a complete decline reason.
How Does Beneficial Ownership Fit Without Overclaiming?
Entity verification and beneficial-owner identification are separate controls. FinCEN's Customer Due Diligence rule applies to named categories of covered financial institutions and describes procedures for identifying and verifying legal-entity customers and beneficial owners.[7] That scope should not be generalized to every nonbank real estate lender.
The practical distinction remains valuable: an EIN match validates a submitted business tax pair. It does not identify the natural people who own or control the company. Counsel and compliance leaders should define the obligations applicable to the lender, product, jurisdiction, funding relationships, and transaction.
What Should the Audit File Retain?
Retain a versioned record that lets a reviewer reproduce the identity decision:
• Original and normalized legal names.
• State entity IDs and source timestamps.
• Exact entity-role map used for the transaction.
• Masked EIN inputs and match results.
• Property and account evidence references.
• Relationship documents for SPE, parent, operator, or manager structures.
• Exception notes, owner, and closure reason.
• Policy version and authorized outcome.
The W-9 requester instructions describe collecting a payee's certified name and TIN.[8] In lending operations, that document can support correction, but it should not replace the record of what the system originally checked.
What Should Teams Monitor After Launch?
Track identity quality independently from credit performance:
1. Files with more than one legal entity.
2. EIN mismatches by intake source.
3. Borrower and title-holder differences.
4. Borrower and account-holder differences.
5. Operating-company evidence used for an SPE borrower.
6. Source-unavailable retries and aging.
7. Manual exceptions by cause and resolution.
8. Overrides by policy version.
These measures show whether the entity map is reducing ambiguity. They do not prove a change in approval quality or loss performance without separate evidence.
What Is the Practical Verification Sequence?
Identify every material legal party, assign its transaction role, locate its relevant state record, validate each required legal-name and EIN pair, reconcile title and account evidence, document relationships, and only then pass the file to credit decisioning.
Cobalt can supply TIN/EIN validation and state entity data. The lender owns the property evidence, beneficial-owner process, relationship analysis, account control, policy, and decision.
Ready to test an entity-role map on a borrower, SPE, and operating-company case? Schedule a Cobalt Intelligence demo and bring the exact identity fields your current workflow preserves.