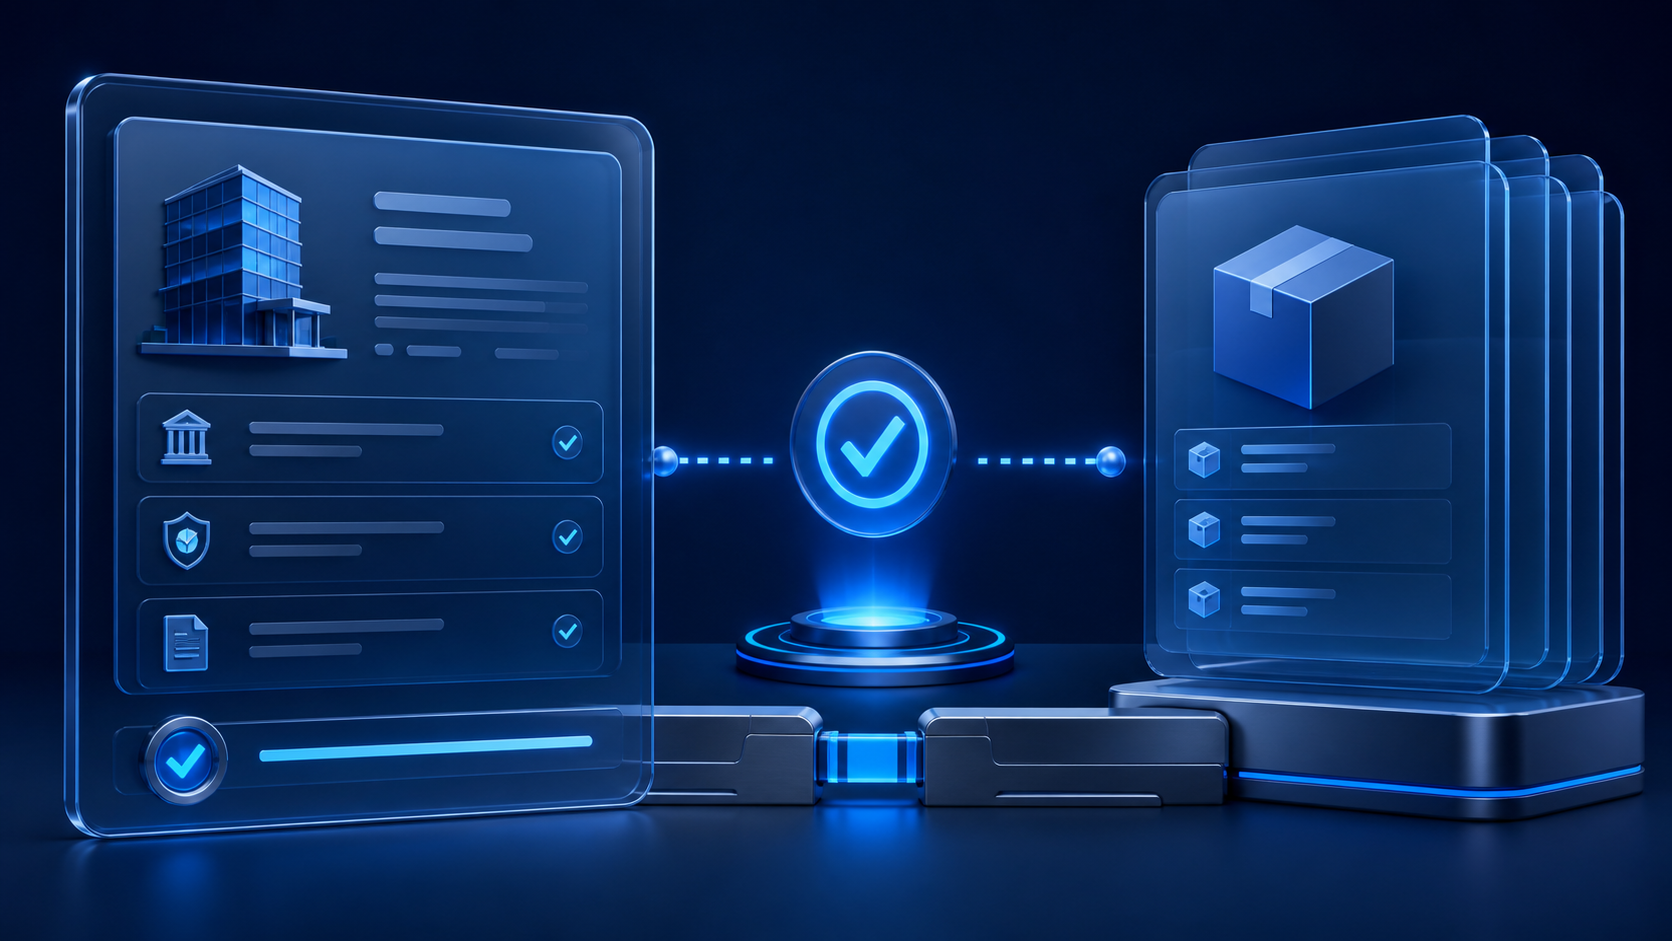
Executive Summary: B2B buy now, pay later providers can keep checkout fast only when the commercial credit account is bound to the legal business behind the order before a limit or shipment is released. A domain, storefront name, email address, or returning buyer profile is not the borrower. EIN verification supplies one narrow control: it tests whether the submitted legal-name and EIN pair matches the source record. That match does not authorize the user, verify the shipping address, confirm account ownership, or approve credit. The provider must connect the verified legal entity to the buyer account and govern how later orders inherit that identity.
Why Does B2B BNPL Need a Legal-Entity Anchor?
Embedded trade credit compresses onboarding, ordering, underwriting, and fulfillment into one journey. That convenience can blur several subjects:
• The person placing the order.
• The platform or merchant account.
• The displayed DBA.
• The legal business accepting credit terms.
• The ship-to location.
• The bank account used for repayment.
• A parent, branch, franchise, or subsidiary.
If the system treats those records as interchangeable, a clean order history can be attached to the wrong legal obligor.
Reusable checkout identity should inherit from a verified legal customer, not from a browser session or display name.
What Does EIN Verification Actually Check?
The IRS TIN Matching program compares a supplied name and TIN combination for eligible payer workflows.[1] Cobalt's documented TIN/EIN endpoint similarly validates a submitted business name and EIN and returns the source result, service status, and timing context.[2]
What remains outside the result?
An EIN match does not prove:
• The checkout user is authorized to bind the business.
• The order or shipping address is legitimate.
• The buyer controls the submitted bank account.
• The business is in good standing in a particular state.
• The business can repay the credit.
• The order should receive a particular limit.
The provider owns those controls and the final decision.
Which Name Should Be Submitted?
Use the legal name associated with the EIN, not the website brand or DBA by default. IRS guidance explains that corporate name control is derived from the legal name and excludes DBA text.[3]
What should checkout collect?
1. Legal business name.
2. DBA or storefront name as a separate alias.
3. EIN under sensitive-data controls.
4. Formation or registration state.
5. State entity identifier when resolved.
6. User role and authorization evidence.
7. Billing and shipping relationships.
8. Parent, branch, franchise, or subsidiary relationship where relevant.
Preserve both the submitted and normalized names. Silent edits make the result impossible to reproduce and may change which entity the system checked.
Where Should the Check Run?
Run it after enough information exists to identify the legal customer but before a credit limit, binding term, or shipment can rely on that identity.
account created
  -> legal entity resolved
  -> legal-name and EIN pair checked
  -> user authority connected
  -> credit policy applied
  -> order released
For returning buyers, reuse the identity record only while the legal customer and material fields remain unchanged. An old match should not automatically cover a renamed entity, new subsidiary, acquired account, or different party placing an order.
How Should SOS Data Support the Account?
State entity data answers a different question from the EIN result. It can anchor the legal name, state identifier, registration, and state-specific status fields. Those fields and their meanings vary by jurisdiction.
SBA guidance distinguishes formation from foreign qualification, which matters when a buyer operates across states.[4] A hit in the shipping state may be a foreign registration of the same entity rather than a new borrower.
What if several records look similar?
Keep every result as a candidate until identifiers, jurisdiction, addresses, and other available evidence resolve the entity. Do not select the first exact-looking name and attach its EIN status to the order.
See EIN Verification and SOS Data: The Two-Source Pattern for the separate assertions these sources support.
How Should a Returning Buyer Inherit Verification?
Store verification as versioned evidence attached to a legal customer master. Then link platform accounts, locations, users, and orders to that master.
What should invalidate inheritance?
• Legal-name change.
• EIN change.
• New legal subsidiary or franchisee.
• Ownership or control event that triggers policy review.
• New financing recipient.
• Unresolved account transfer.
• Verification age beyond the provider's policy.
• Material mismatch in state, bank, billing, or shipping evidence.
The inheritance rule should record which prior event was reused and why. A mutable green checkbox cannot show whether the exact pair on the current order was ever checked.
What Should the Routing Table Do?
• Match and consistent entity. Continue to authorization and credit controls.
• Name mismatch. Request corrected legal-name or tax evidence and rerun the pair.
• No match. Classify the reason and stop automatic release.
• Source unavailable. Retry or hold. Do not convert absence of evidence into a pass.
• DBA only. Resolve the legal entity before checking the EIN.
• Different subsidiary. Create or verify a separate legal-customer record.
• User not linked to entity. Require authorization evidence before binding terms.
• Ship-to or bank inconsistency. Route under the provider's fraud and account-control policy.
IRS Publication 1281 provides correction procedures for incorrect name/TIN combinations in its reporting context.[5] The useful workflow principle is that a mismatch can be corrected or reviewed. It does not automatically establish fraud.
How Should Authorization Stay Separate?
Legal-entity verification answers who the business is. Authorization answers whether this person may act for it. The provider may use verified domains, role-based invitations, account administrators, contracts, or other evidence under its policy, but should not infer authority from an EIN match.
The same separation applies to credit. A match can permit the verified identity to enter a decisioning process. It cannot determine the limit or release the order.
For pre-funding placement of the control, see Why EIN Verification Belongs in Pre-Funding, Not Post-Approval.
What Should the Audit Trail Preserve?
1. Original checkout values.
2. Legal customer ID.
3. State entity record and identifier.
4. Masked EIN and exact name used.
5. Match result, reason, service status, and timestamp.
6. User-to-business authorization evidence.
7. Account, location, and order links.
8. Policy version, exceptions, and outcome.
The IRS publishes requester instructions for Form W-9, which can support a correction path by obtaining a certified name and TIN.[6] Preserve the correction alongside the original event rather than overwriting history.
What Should Product and Risk Teams Monitor?
• First-order match rate.
• DBA-related correction rate.
• Returning orders inheriting prior evidence.
• Inheritance invalidations by cause.
• Multiple-entity buyers.
• User-authorization exceptions.
• Source-unavailable aging.
• Orders held after identity passed but account or address evidence disagreed.
These measures reveal whether identity reuse is controlled. They do not establish a change in conversion, fraud loss, or credit performance without separate outcome evidence.
What Is the Practical B2B BNPL Sequence?
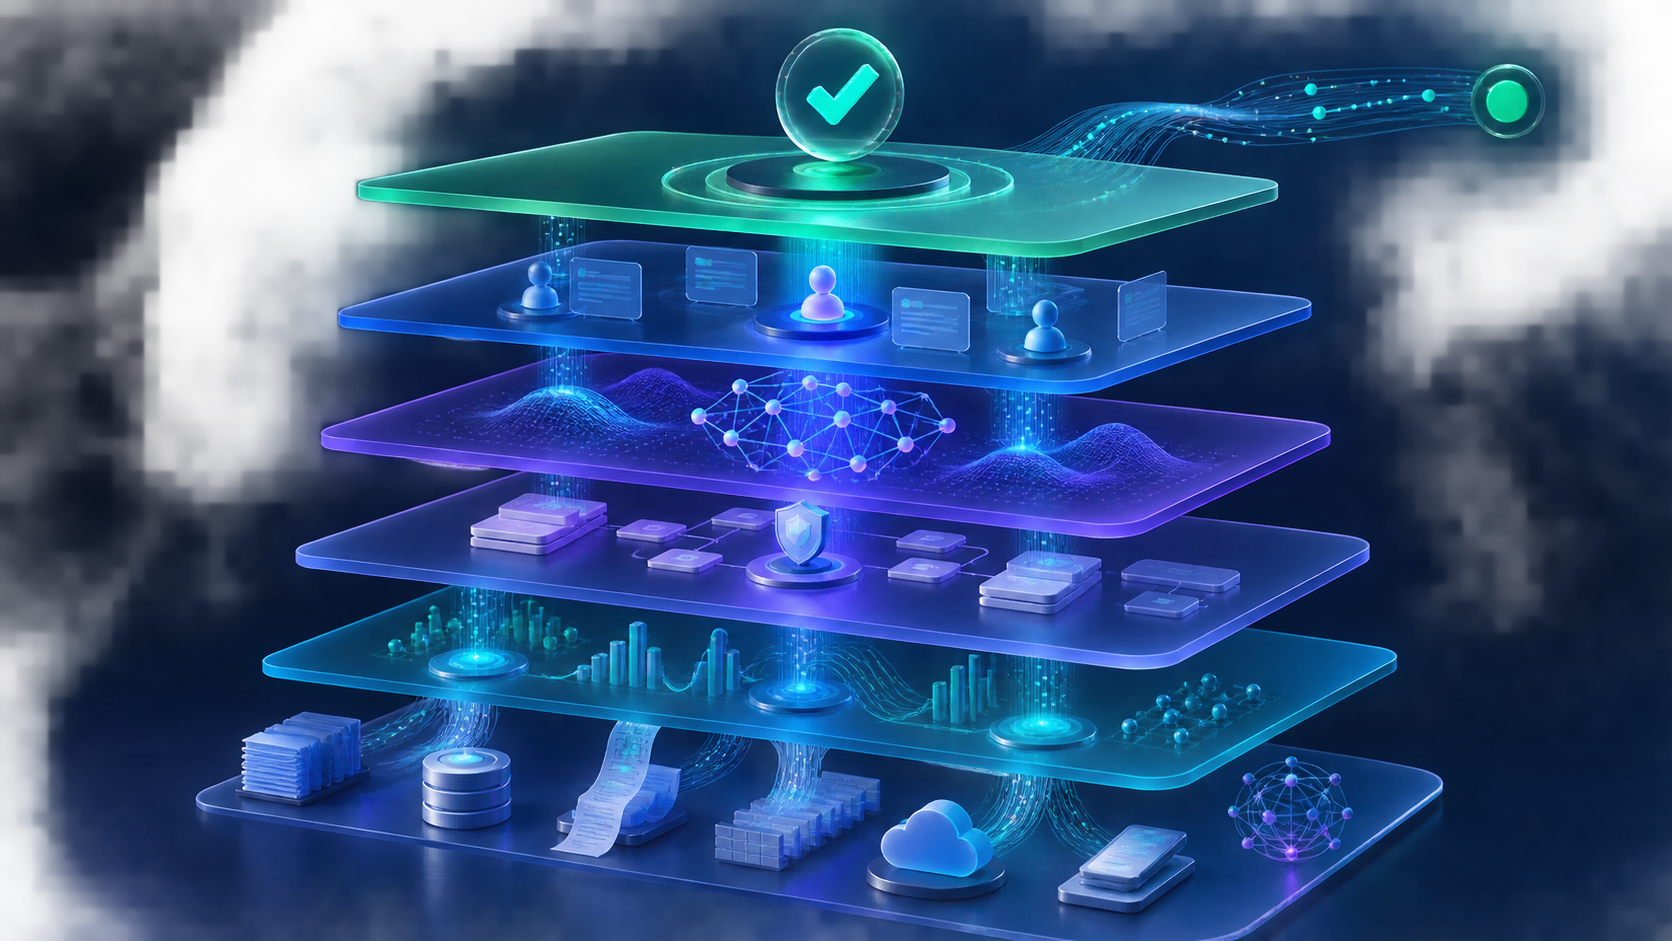
Resolve the legal business, validate its name and EIN pair, connect the state record, bind authorized users and platform accounts to the legal customer, apply credit policy, then release the order. Later orders may inherit the verified identity only under a versioned refresh rule.
Cobalt supplies the tax-pair and state-source results. The provider owns user authorization, account relationships, order checks, limits, credit decisions, and fulfillment.
Ready to test one first-order case, one DBA case, and one returning-buyer change? Schedule a Cobalt Intelligence demo and bring the identity fields your checkout currently stores.